The True Cost of Jumping Chains: What NFT Investors Lose When Chasing the Next Hot Blockchain
The narrative is familiar to anyone who has spent time in active NFT markets. A collection gains traction on a new blockchain, trading volumes spike, floor prices climb, and investors holding comparable assets on older networks begin calculating what it would take to migrate their portfolios. The logic appears sound: follow the momentum, position ahead of the crowd, capture the premium that newer ecosystems command during their growth phase.
What this calculus routinely omits is the full accounting of what migration actually costs—not just in transaction fees, but in slippage, tax obligations, smart contract exposure, and the timing risks that compound with each step of the process. For many investors, the destination chain delivers returns that are substantially lower than projected, precisely because the migration itself consumed the margin they were attempting to capture.
The Bridge Is Not a Door: Understanding Structural Transfer Costs
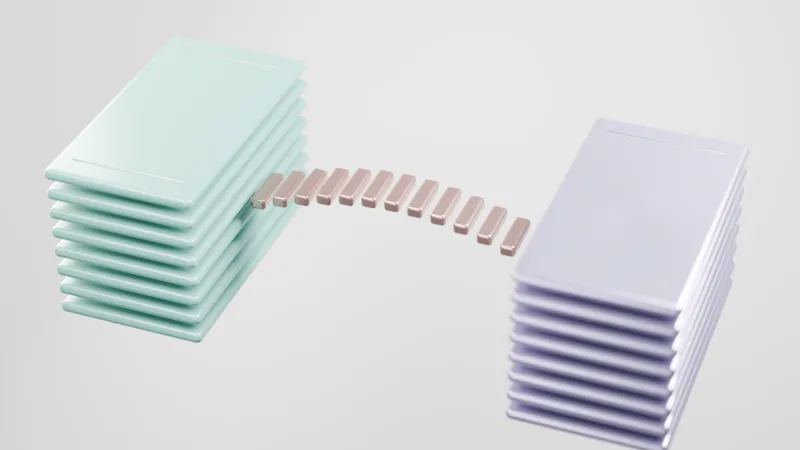
Cross-chain bridges are the primary mechanism through which digital assets move between blockchain networks. They vary considerably in design—some operate through lock-and-mint models, others through liquidity pool mechanisms—but all of them introduce costs and risks that are frequently underestimated by retail investors.
The most visible cost is the bridge fee itself, which typically ranges from a fraction of a percent to several percent of the asset's value, depending on the networks involved and current congestion levels. On high-value NFTs, this is meaningful but manageable. On collections trading near or below mint price, bridge fees can represent a significant portion of remaining value.
More consequential, and far less visible, is slippage. When a bridge relies on liquidity pools to facilitate transfers, the execution price of the transfer is subject to the depth of available liquidity at the moment of the transaction. Investors moving large positions—or operating during periods of elevated network activity—may receive substantially less than the quoted rate. Unlike exchange slippage, bridge slippage is often not displayed prominently before a transaction is confirmed, leaving investors to discover the shortfall after the fact.
Gas costs on both the origin and destination chains add another layer. A migration that requires multiple contract interactions—approving the bridge contract, initiating the transfer, claiming on the destination chain, and then listing or repositioning the asset—can generate gas expenditures that, in aggregate, rival the bridge fee itself.
Tax Recognition: The Obligation That Investors Consistently Overlook
Perhaps the most financially significant and least discussed cost of cross-chain migration is the tax event it may trigger. Under current IRS guidance, the disposition of a digital asset—including through a bridge mechanism—constitutes a taxable event if it results in the exchange of one asset for another.
The specific tax treatment depends on the bridge's technical architecture. In a lock-and-mint model, the original NFT is locked in a smart contract while a wrapped or synthetic version is issued on the destination chain. Whether the IRS treats this as a disposition of the original asset or a continuation of the same position is a question that lacks definitive published guidance—but the conservative and defensible interpretation is that a taxable exchange has occurred.
For investors holding NFTs with significant unrealized appreciation, this means that a migration decision carries an embedded tax liability that must be factored into the return calculation before any transfer is initiated. An NFT purchased for 0.5 ETH and currently valued at 3 ETH carries an implied gain of 2.5 ETH. If migration triggers recognition of that gain, the after-tax cost of the transfer could easily exceed the expected benefit of repositioning on a new chain.
This dynamic is particularly acute for long-term holders who have accumulated substantial unrealized gains. The portfolio optimization logic that drives migration decisions—moving assets to where liquidity and demand are stronger—does not automatically survive contact with a realistic tax-adjusted return model.
Smart Contract Exposure During Transit
Bridges are consistently among the most exploited infrastructure components in the Web3 ecosystem. The technical architecture that enables cross-chain transfers requires smart contracts to hold significant asset value in custody during the transfer process, creating concentrated targets for malicious actors.
Several high-profile bridge exploits have resulted in total or near-total losses for assets in transit. While major bridge operators have implemented progressively more sophisticated security frameworks, the fundamental risk of holding assets in a bridge contract—even briefly—is not zero. Investors migrating large or high-value positions should evaluate the audit history, insurance coverage, and incident response track record of any bridge they intend to use.
Beyond outright exploits, there is the subtler risk of smart contract failure during periods of network congestion. Transactions that initiate on the origin chain but fail to complete on the destination chain can result in assets being locked in bridge contracts for extended periods—sometimes permanently, if the contract lacks adequate recovery mechanisms.
Timing Risk and the Momentum Trap
The decision to migrate an NFT portfolio is typically made in response to observable momentum on the destination chain. By definition, this means the decision is being made after the signal has already become visible to the market—and often after significant price appreciation has already occurred.
The time required to execute a migration—researching bridge options, executing approvals, completing transfers, and relisting assets—can span hours to days depending on network conditions and asset volume. In fast-moving markets, this window is sufficient for momentum to shift materially. Investors who initiate migrations in response to a trend may find themselves completing those migrations as the trend decelerates.
This is not a theoretical risk. Post-migration analyses of investor behavior during several major chain-migration events have shown that a meaningful percentage of participants underperformed simply holding their original positions, once all transfer costs and timing effects were accounted for.
A Framework for Evaluating Migration Decisions
None of this argues that cross-chain migration is never rational. There are circumstances—particularly when destination chain liquidity is demonstrably superior and the migrating investor holds assets with minimal embedded gains—where the expected value of migration is clearly positive.
The discipline required is a complete cost accounting before any transfer is initiated. That accounting should include:
- Bridge fees and estimated slippage at current liquidity depth
- Gas costs for all required contract interactions on both chains
- Tax liability triggered by the transfer, calculated at the investor's marginal rate
- An honest assessment of whether the destination chain's current momentum is early-stage or already mature
- The opportunity cost of capital and attention during the migration window
Investors who work through this framework carefully will find that many migrations that appear attractive on a gross basis are marginal or negative on a net basis. That is not a reason to avoid cross-chain positioning entirely. It is a reason to approach it with the same rigor applied to any other significant portfolio decision.